



TAMPA, Fla. — We pay hundreds, sometimes thousands of dollars a year for health insurance, expecting it to save us money when we need care. But what if using that insurance doesn't always get you the better price?
One Tampa mom's leap away from coverage
For one South Tampa mom, routine brings comfortin routine —a clean kitchen, her kids' calendar, knowing what tomorrow will bring. But when it comes to health care, Laura Kissak believes comfort doesn't mean necessary. And she did something years ago many families would consider unthinkable: She dropped health insurance altogether.
"Our family's been self-paying for about 7 years since my youngest was born," Kissak said.
She said the cost was what drove the decision.
"It was just the biggest expense, more than the mortgage," Kissak said.
But adds it was a scary decision to make.
"You're just going to die, you know, you're going to be bankrupt, the world's gonna end, and I totally believe that, like how, you know, how dare you go without coverage, you know, um, but you know you kind of ease into it and it gets better," Kissak said.
She has since created the Facebook page Self Pay Tampa Bay, where she's finding there are more people like her.
"We took the leap and left traditional health insurance," her post read. "As a business owner family, premiums were 2K a month with a 10K deductible."
She now pays about $200 for a monthly membership at a doctor who offers cash options for her entire family.
"We were having the experience where the self-pay price was cheaper than even after insurance," Kissak said. "I always remember like still getting a bill for $400 from Quest even after insurance, like just for a simple blood draw, and the primary care we use now does a blood draw in the office, and it's about $20 just for a simple blood work."
But understands there is risk. Kissak and her family the money they would be paying for health insurance premiums into an account each month and increased the bodily injury and liability coverage on her car insurance.
"I mean, maybe for catastrophic things, but even then we've been putting the money aside now and what we would have spent on premiums, we should be able to still even self fund some of that," Kissak said.
Testing the prices in dollars and cents
We wanted to see what this actually looks like in dollars and cents. So we went into hospital price estimators and searched some of the most common health care needs: blood work, an office visit, a colonoscopy and a mammogram. For most, the estimates were pretty similar, or insurance came out a little cheaper.
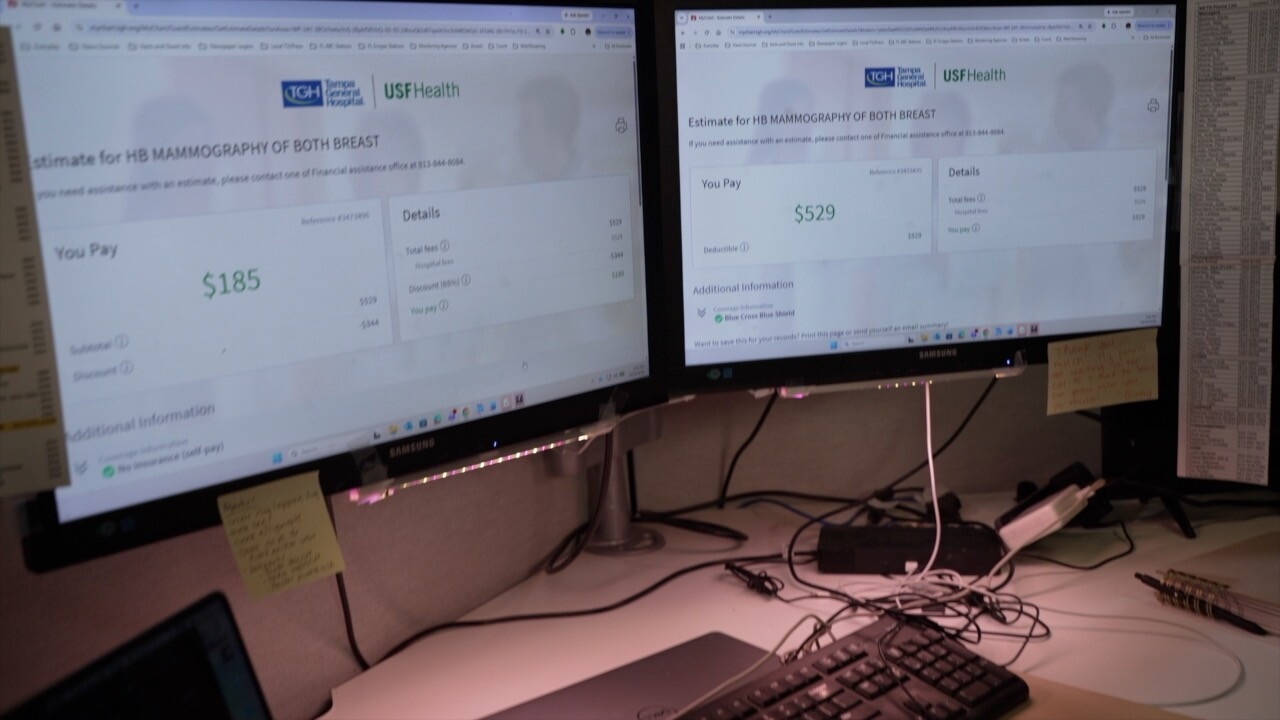
But then we tested the prices for a bilateral mammogram. Using Tampa General Hospital's estimator, our mammogram estimate with insurance was $529. The self-pay estimate? $185. Same search. Same medicine. The money is different — $344 in this case.
In fact, researchers at Johns Hopkins studied prices for 70 common, shoppable health care services at 2,379 hospitals across the country. They found 47% of those hospitals had cash prices that were lower than or the same as the price negotiated by the insurance company.
What a professor says about the trade-offs
Dr. Jay Wolfson is a professor at USF's Morsani College of Medicine. He said growing demand for self-pay options is a reflection of broader changes.
"It's a reflection of the changes in the health care system that have been brought about in, in fair part by the failures of the Affordable Care Act to do what it was intended to do," Wolfson said.
"The market's a wonderful thing. It's a wonderful thing. You don't have to be a big insurance company necessarily to play it," Wolfson said. "And if they can afford to do it and if they're in good health, maybe it makes sense for some people to say, I'm gonna stash the money away. Not everybody can afford to do that."
A lower cash price doesn't necessarily mean insurance isn't worth having, he said.
"Now if your employer offers it, take it. And if the price for a policy is reasonable, take it," Wolfson said.
While you can shop around for routine care, he said an unexpected illness or emergency can change the math quickly.
"But don't, don't bargain with your own health. It's not a roulette wheel," Wolfson said.
So his advice during open enrollment: Do your homework. Compare your options, know what your plan covers and what it costs, and don't assume the insurance price is always the lowest price. And whether you're using insurance or paying cash, he said it pays to ask.
"It never hurts to negotiate," Wolfson said.
Kissak said the right choice is a personal one.
"It's just, what it's, once again it's whatever works for your family. Every family is going to be on this. It's whatever you're comfortable with, your risk tolerance," Kissak said.
Hospital Price Estimators
Each hospital group has a price estimator tool for you to test out cash prices versus insurance prices yourself. Take a look:
Pasco County mom of 5 takes in 3 children left without food or power whose mother faces neglect charges
Jasmine Young, a mother of 5, opened her home to three neglected girls as their mother faces child neglect charges for leaving them without food, power or water.
